KRW Accountants to rebrand to Affinia
Keith Witchell
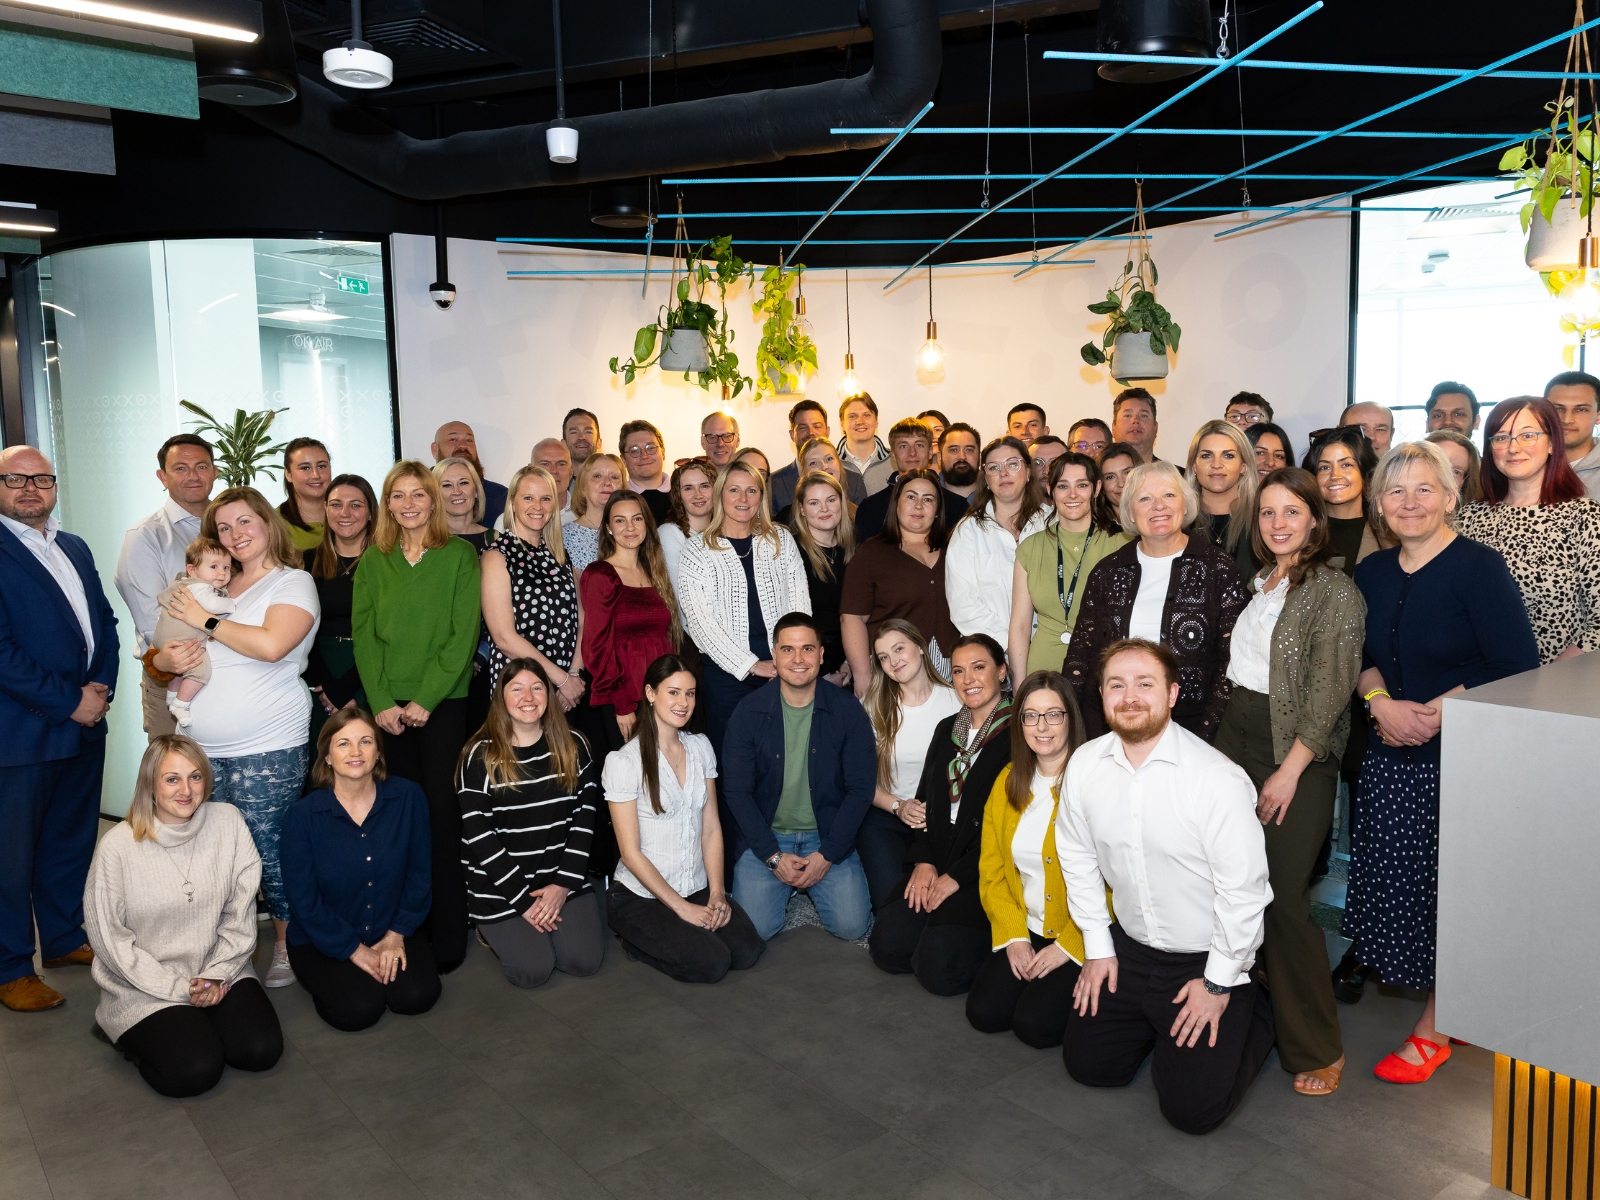
Following our news in April that we have joined the Affinia Group, we will be adopting the Affinia branding from next month onwards.
Our business combination with Affinia all happened quite quickly. We first met in January to explore the potential sale of the practice, which is something we’d always planned to do in the future, so we thought it made sense to start to understand what that might look like. Typically, we really liked the guys at Affinia and their approach, and they quickly allayed our fears around being swallowed up by a ‘big firm’, as Affinia aren’t like the big accountancy firms. They’re essentially a collection of smaller firms, focused on small and medium sized business clients like we are. We liked everyone we met and it felt like a good fit; they made us an offer, there was a bit of negotiation, and then we reached an agreement in February. Some due diligence followed, and we completed the deal in early April.
Almost six months on, and I’m pleased to say that things are going well. We’ve changed some of our practice software, and some of our administrative functions have been centralised, but otherwise it has been business as usual, only with added support and expertise to better support our clients.
Our team remain largely the same, although our superstar Practice Manager Sandra Franklin has retired, and we bid her a fond farewell last month, after 17 years at the helm! We’re also sad to report that Alice Burt will be leaving us at the end of this month. However, the rest of the team remain the same.
Next month will see us rebrand from KRW to Affinia. Affinia’s Head of People joked that I would need to change my numberplate, until I pointed out that they would still be my initials!! I have no plans to change my name, although I’d be lying if I said I hadn’t contemplated it many times over the years…!!
Our website will be updated with the Affinia branding, and we’ll have new office signage, plus accounts and other documents will say Affinia instead of KRW Accountants. We’ll all have new email addresses too, although the existing ones will continue to work, to ensure seamless continuity.
Credit control will also be centralised, and will become more automated.
Apart from this though, it’s very much business as usual, but with access to additional expertise within the group, such as Corporate Finance to support clients selling or refinancing their businesses, specialist VAT and international tax, and links to accountancy firms outside the UK, such as UHY in Ireland and the USA in particular. We’ve already seen the benefit of these additional resources, which will allow us to better support our clients moving forwards.
So please be ready for future communications from us from next month onwards to be from Affinia. Different name, but the same great service!
Please contact your Client Manager or myself or Alex Beattie if you have any questions about these changes; we’re very happy to help.
- We joined the Affinia Group in April 2026.
- Not much has changed, other than some software, and centralising some of our administration.
- We bid a fond farewell to our Practice Manager Sandra last month after 17 legendary years.
- Alice Burt is also leaving us; but the rest of the team remain the same.
- Be ready for communications in the Affinia name from next month.
For more information, please contact me.
Q&A: How much can I claim per mile for charging my electric company car?
Keith Witchell
Business owners with electric company cars often ask us how much they can claim for the cost of charging their vehicles at home, or when out and about using public chargers.
HMRC publish advisory fuel rates on their website quarterly, with the rates used to work out the amount you can reimburse yourself for any business journeys in a company car.
These rates are published on the 1st March, 1st June, 1st September and 1st December each year, to ensure that the approved mileage rates are aligned with the current cost of fuel/electricity.
For company Directors/owners with electric or hybrid company cars (see this month’s Tax Tip article for more information on the merits of getting one) that pay for the fuel or charging themselves, these rates can be used in order to be reimbursed for any business journeys covered in the car.
From 1 September 2026, the following rates apply:
Petrol
| Engine size | Petrol — rate per mile | LPG — rate per mile |
| 1400cc or less | 14 pence | 11 pence |
| 1401cc to 2000cc | 17 pence | 13 pence |
| Over 2000cc | 27 pence | 20 pence |
Diesel
| Engine size | Diesel — rate per mile |
| 1600cc or less | 15 pence |
| 1601cc to 2000cc | 16 pence |
| Over 2000cc | 22 pence |
Electric
| Charging location | Electric — rate per mile |
| Home charger | 7 pence |
| Public charger | 15 pence |
For electric cars a new public charger rate was introduced last year, which can be used for business journeys covered in your electric company car, where you had to use a public charger. It’s great to see that HMRC are acknowledging the fact that using a public charger is significantly more expensive than charging at home.
For anyone that regularly uses public chargers for business journeys we’d encourage you to keep receipts as evidence, to support reclaiming your business mileage for those trips at the higher 15p per mile rate.
This is also a useful recap that business mileage in an electric or hybrid company car can be reimbursed to you, in the same way as claiming 55p per mile for using your own car for business journeys.
We had an interesting question from a client recently that stumped half of our team. A client bought an electric car through his limited company, for use by his wife for purely personal journeys. We prepare a P11D for him, and he pays tax on the company car benefit in kind each year, but had continued to use his own personally owned car for business journeys. Could he claim 55p per mile for those journeys like he used to? Or did having an electric company car prevent him from doing so? He was pleased to learn that he could of course continue to claim 55p per mile for business journeys travelled in his own car. Having an electric company car doesn’t mean he has to use that vehicle for business journeys. He is paying tax on the benefit in kind of the electric company car being made available to him (and his family) for private use, and that calculation is based on the list price of the car, regardless of how much it is used for business. So there is nothing to stop him continuing to use his own car for business journeys, and claiming back 55p per mile from his company to cover the cost of the fuel and running costs of that vehicle. Another happy client!
If you have any questions on how to use the advisory fuel rates in your business, then please contact your Client Manager.
- HMRC advisory fuel rates are published every quarter, most recently on 1st September 2026
- Use these rates to claim for business mileage in a company car if you pay for the fuel or charging
- The main electric car rate is 7p per mile; if you use a public charger the rate is 15p per mile
- If you use your own vehicle for business journeys, you can claim 55p per mile
- This applies even if you also have an electric company car, if you have the use of both vehicles
For more information, please contact me.
Tax tip: Electric cars remain a tax-efficient perk for company owners
Keith Witchell
From April 2026 the benefit in kind tax on electric cars increased from 3% to 4%, while the bands for hybrids also increased by 1%, with both set to rise by 1% again next tax year.
The following bands apply to vehicles emitting up to 50g/km of Co2:
| CO2 emissions g/km | Electric range | 2026/27 | 2027/28 | 2028/29 |
| 0 | n/a | 4 | 5 | 7 |
| 1-50 | >130 miles | 4 | 5 | 18 |
| 1-50 | 70-129 miles | 7 | 8 | 18 |
| 1-50 | 40-69 miles | 10 | 11 | 18 |
| 1-50 | 30-39 miles | 14 | 15 | 18 |
| 1-50 | <30 miles | 16 | 17 | 18 |
Electric cars have zero emissions so are in the first category. Meanwhile, more and more hybrid models are being launched that emit less than 50g/km of Co2 and fall into the 70-129 mile category, which still carries a low BIK rate of 7%.
You’ll be doing well to find many options that can cover more than 130 miles on electric range only, so while that category of hybrids enjoy the same benefit in kind rates as pure electric cars, we are yet to see any real world examples among our client base!
Under current legislation, the table above shows that the BIK percentage for hybrids is set to increase to 18% across the board from April 2028 onwards; while the BIK percentage for electric cars is set to increase by 2% to 7%. This may be revised in future Budgets, but this means that hybrids become less tax efficient from 2028/29 onwards, leaving electric cars as the safer bet to maximise tax savings.
The percentages in the table above are applied to the list price of your chosen car when new to work out the benefit in kind, which will then be reported to HMRC (with our help) on a form P11D. You will then have to pay personal tax on the benefit in kind (typically at 20%), while your company will have to pay 15% Class 1A National Insurance annually on the same value.
So there are some taxes to pay if your company buys an electric or hybrid car for you to use, but they are manageable.
The advantage of doing so is that the company can then claim Corporation Tax relief on the costs of buying or leasing the vehicle, plus insurance, servicing, tyres and repairs.
If you buy an electric vehicle brand new, whether outright or on finance, your company can claim capital allowances of 100% on the price paid for the vehicle in the year of purchase. You’ll therefore save (up to) 25% Corporation Tax on the value of the vehicle. The downside of doing so is that your company will then have to pay Corporation Tax on the sale proceeds in the future when you come to sell it, but this offers a great front-loaded tax incentive to significantly reduce your Corporation Tax bill in the year you buy it.
This 100% first year allowance for buying a new electric car is due to end on 31 March 2027, making this a great time to consider making the change to electric, before that front-loaded Corporation Tax saving opportunity comes to an end.
Alternatively, if you lease it then you can claim tax relief on the lease payments, which means the Corporation tax relief is more evenly spread across the period you have the car. A further advantage to leasing is that you can reclaim half of the VAT on the monthly lease payments, if you are VAT registered, whereas no VAT recovery is possible if you buy it (outright or on finance).
What about hybrids? The 100% capital allowance mentioned above is only available for (brand new) pure electric cars, with hybrids attracting capital allowances of 18% per annum, meaning the tax relief for buying a hybrid vehicle are spread more evenly, much like leasing one. This 18% capital allowance equally applies to new or used hybrid vehicles (providing they emit less than 50 g/km of Co2) and the same rate also applies to the purchase of second hand pure electric vehicles.
In both cases the company can also pay for the running costs, including insurance, servicing, tyres and repairs, with VAT also reclaimable on those costs if you are VAT registered. Your company can also reimburse you for home charging costs, using HMRC approved business mileage rates (see Q&A article).
Many business owners want to keep their incomes below the higher rate threshold of £50,270, to avoid higher rate tax, or under £60,000 to avoid the High Income Child Benefit Charge, but with the cost of living rising year on year and these thresholds staying frozen, this is becoming increasing difficult. For those clients that use part of the funds they withdraw from their companies in salary and dividends to make finance payments on a personally owned car, then why not buy an electric car through your company so that your salary and dividends go further? Every little helps!
For more information, please contact your Client Manager.
- Company car tax on electric vehicles increased to 4% from April 2026
- The bands for hybrids also increased by 1%, but will increase to 18% from April 2028
- Corporation Tax and VAT savings can be made on buying/running the vehicle
- 100% first year capital allowance still available for purchasing new electric cars until March 2027
- Get your company to pay for your car so that your salary and dividends go further
For more information, please contact me.
Andy Burnham shows support for pubs with 20% business rates reduction
Keith Witchell
Within days of entering no 10, Prime Minister Andy Burnham announced that pubs, social clubs and live music venues in England will be given a 20% cut to business rates from April 2027.
When this measure was announced, Andy Burnham said that pubs in particular “need to know that the cavalry is coming”, clearly signalling his support for the hospitality sector, which is currently facing record numbers of closures and business failures.
This announcement followed the 15% cut in business rates for pubs and music venues from April 2026, announced by the previous Chancellor Rachel Reeves.
However, these rates cuts do not apply to hotels and restaurants, many of which are also struggling to make a profit, and these businesses are also in desperate need of government support.
Furthermore, these rates cuts follow increases to rateable values in April 2026, which saw rates increase substantially for many businesses in the sector, as the previous covid rates relief was also withdrawn on the same date. As a result, many pub landlords see the 15% and 20% cuts as merely chipping away at the increases imposed in April, as opposed to a saving.
With the hospitality sector really struggling, and with record numbers of business failures, there’s a genuine fear that local pubs, restaurants and café’s will not be able to survive, without further help.
This has been widely covered in the media and you may have seen the VAT’s the Problem campaign, the petition spearheaded by celebrity chef Tom Kerridge, which is calling for a cut in the VAT rate for the sector to 10%, in line with the majority of other European countries that have lower VAT rates for hospitality businesses. This would provide more permanent help for the sector, bringing many businesses back into profit, and allowing them to invest and grow, as opposed to fighting for survival.
They are aiming for 1 million signatures, and are close to 400,000. Signing the petition is really quick and easy, so if you care about your local pub, restaurant or café staying open, you can sign it here .
We have many clients in the hospitality sector, and have seen most of these struggle since the reduced covid VAT rates came to an end in March 2022, indicating the pressure that this sector is under currently. We hope that Andy Burnham’s rates cut announcement back in July when he took office will lead to further support measures in new Chancellor John Healey’s Budget on 28 October 2026.
For further information on this matter please don’t hesitate to contact me.
- Andy Burnham announced a 20% business rates cut for pubs and music venues from April 2027
- He also indicated further support measures for the sector by saying “the cavalry is coming”
- This followed a 15% rates cut from April 2026, to alleviate increases in rateable values
- No rates relief was given to restaurants and hotels, but the whole hospitality sector is struggling
- We hope to see further support measures in the Budget next month
For more information, please contact me.
Cash ISA allowance will be reduced from £20k to £12k from April 2027
Keith Witchell
For more information, please contact me.
Mansion tax for homes worth over £2M from April 2028
Keith Witchell
For more information, please contact me.
100% CGT relief for shares sold to employee ownership trust halved
Keith Witchell
For more information, please contact me.
Permanent rates reduction for hospitality, retail and leisure
Keith Witchell
For more information, please contact me.
NIC to apply to salary sacrifice pension arrangements from April 2029
Keith Witchell
For more information, please contact me.
Mileage based electric/hybrid vehicle excise duty from April 2028
Keith Witchell
For more information, please contact me.